Rebuild Credit: Veterans Overcoming Financial Hardship
Veterans, Credit Rebuilding, Financial Hardship, Debt Management, Credit Score Tips, Financial Wellness
How Veterans Can Rebuild Credit After Financial Hardship
Coming home from service should feel like a new beginning, not the start of a long fight with bills, collections, and a damaged credit score. Yet many Veterans find themselves facing financial hardship after discharge, transition, or deployment. The good news is that credit rebuilding is absolutely possible, and you do not have to figure it out alone. With the right information, practical steps, and support, you can move from survival mode toward long-term financial wellness.
Why Financial Hardship Hits Veterans So Hard
Financial hardship can affect anyone, but Veterans often face a unique set of pressures. Transitioning from military to civilian life can mean changes in income, location, routine, and identity all at once. A delay in benefits, a gap between jobs, or unexpected medical costs can quickly turn into missed payments, growing debt, and a falling credit score. None of this is a reflection of your character or your service; it is a reflection of a system that is often confusing and unforgiving when money is tight.
Many Veterans also carry responsibilities that others do not see: supporting family members, managing service-connected injuries, or coping with mental health challenges. When energy is going toward healing and adjusting, it is easy for credit card statements or loan notices to pile up. Over time, those missed or late payments show up on your credit report and can make everyday goals—like renting an apartment, buying a car, or qualifying for a mortgage—feel out of reach. Understanding how this happens is the first step toward intentional credit rebuilding rather than feeling stuck or ashamed.
Understanding Your Credit Score: The Basics That Matter Most
Before you can repair something, it helps to know how it works. A credit score is a three-digit number that reflects how likely you are to repay borrowed money. Lenders use it to decide whether to approve you for credit and what interest rate to offer. Most scoring models look at similar pieces of information, and a few factors carry the most weight. You do not need to become a financial expert, but a basic understanding puts you back in the driver’s seat when it comes to credit score tips and decision-making.
Payment history: Whether you pay bills on time is usually the single biggest factor. Late payments, collections, and charge-offs can drag your score down, while consistent on-time payments help it climb over time.
Credit utilization: This is how much of your available credit you are using. If your credit card is close to its limit, that high balance can hurt your score, even if you make minimum payments on time. Keeping utilization under about 30% is often recommended, and lower is even better when possible.
Length of credit history: Older accounts help show stability. Closing long-standing accounts can sometimes shorten your average history, so it is worth thinking carefully before shutting down an old card—especially if it has no annual fee and is in good standing.
New credit and inquiries: Applying for several new credit accounts in a short period can be a red flag to lenders. A few inquiries will not ruin your score, but it is wise to be selective and intentional when you apply for new credit during the rebuilding phase.
Types of credit: A mix of credit cards, installment loans, and other accounts can help, but it is not necessary to chase every type. For most Veterans working on credit rebuilding, the focus should stay on stability and payment history rather than adding new kinds of debt.
📌 Key Takeaway: You do not have to fix everything at once. Improving just two areas—on-time payments and lowering card balances—can make a noticeable difference in your credit score over time.
Step One in Credit Rebuilding: Get the Full Picture of Your Situation
It is hard to fight what you cannot see. The first step in credit rebuilding after financial hardship is to get a clear, honest picture of where things stand. That means pulling your credit reports, listing your debts, and taking stock of your income and essential expenses. This process can be uncomfortable, especially if you have been avoiding mail or calls from creditors, but it also marks the moment you stop letting your finances happen to you and start directing them with intention.
You are entitled to free credit reports from the major bureaus at regular intervals. Reviewing them carefully helps you spot late payments, collections, and any accounts you do not recognize. If there are errors—such as debts that do not belong to you or incorrect late payment marks—you have the right to dispute them. For Veterans, this is especially important, because deployments, address changes, and benefit transitions can sometimes lead to misreported information. Clearing up mistakes will not solve every problem, but it can prevent your score from being dragged down unfairly.
💡 Pro Tip: Keep a simple notebook or digital file where you record each debt, the balance, the interest rate, and the minimum payment. Seeing everything in one place turns a vague sense of overwhelm into a concrete plan you can work with.
Debt Management Strategies That Respect Your Reality
Once you know what you owe and to whom, the next step is choosing a debt management strategy that fits your life. There is no single “right” method; the best approach is the one you can stick with consistently. For many Veterans, the goal is to reduce stress as well as balances, so it helps to pick a method that feels manageable and clear rather than complicated or punishing.
The Debt Snowball: Building Motivation Through Small Wins
With the debt snowball method, you focus on paying off your smallest balance first while making minimum payments on everything else. Once that smallest debt is gone, you roll the amount you were paying on it into the next-smallest balance. Each time a debt disappears, you gain momentum and confidence. For Veterans who are used to seeing progress and results, this method can feel satisfying and motivating, even if it is not always the fastest way to save on interest.
The Debt Avalanche: Targeting High-Interest Balances First
The debt avalanche method takes a different angle. You focus on the debt with the highest interest rate, regardless of the balance, while paying minimums on the rest. When that high-interest account is paid off, you move to the next-highest rate. This approach can save more money in the long run because you are attacking the most expensive debt first. For Veterans who like the idea of maximizing every dollar, this strategy can feel more efficient and logical, even if early victories are not as visible.
When to Consider Professional Debt Management Support
If juggling multiple payments and dealing with creditors feels overwhelming, a reputable nonprofit credit counseling agency can help. These organizations may offer a debt management plan, where they work with your creditors to potentially lower interest rates and combine payments into one monthly amount. For some Veterans, this structure makes it easier to stay on track and avoid missed payments, which supports both debt reduction and credit rebuilding. It is important to research any organization carefully, watch for high fees, and confirm that they are not pushing you toward options that do not fit your needs or values.
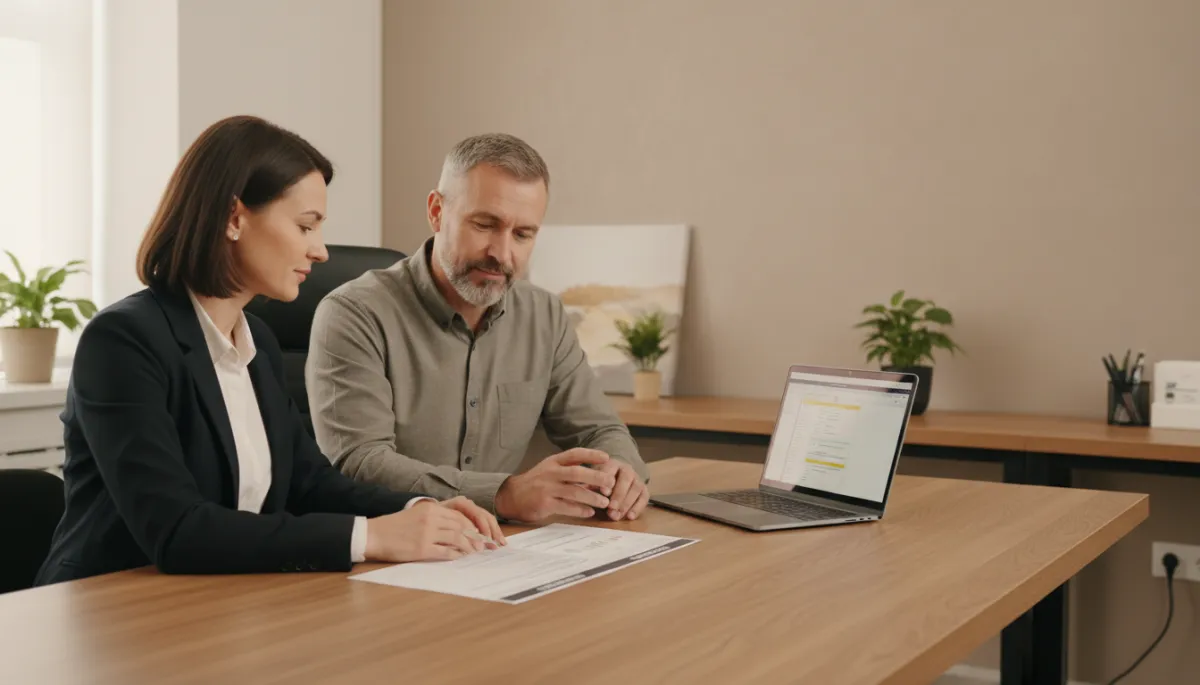
Scene of a Veteran meeting with a financial counselor in a small office, both looking at a...
Sitting with a neutral counselor can turn scattered numbers into a clear debt management plan.
Credit Score Tips Specifically Helpful for Veterans
While the basic rules of credit apply to everyone, there are some credit score tips that can be especially useful for Veterans navigating financial hardship. These suggestions are not quick fixes, but they can make the path to credit rebuilding more direct and less confusing. The goal is not perfection; the goal is steady progress that brings more options and less financial stress over time.
Set up automatic payments when possible: Even if you can only afford minimum payments on certain accounts, automating those payments can help prevent accidental late fees and negative marks on your report. This is especially helpful if you are dealing with health appointments, job changes, or other major transitions that make it easy to lose track of due dates.
Focus on one or two priority accounts: If you have several cards near their limits, consider choosing one to aggressively pay down first. Reducing the balance on a single card can lower your overall utilization and sometimes provide a noticeable boost to your score, even before every account is under control.
Avoid closing old accounts in good standing: If you have an older card that you rarely use but that has no annual fee and a positive history, keeping it open can help your average account age and total available credit. Those details add quiet strength to your credit profile, even if they do not feel dramatic day to day.
Be cautious with new credit offers: After financial hardship, it can be tempting to accept any card or loan offer that appears, especially if it promises “instant approval.” Some of these products come with very high interest rates or fees. Choosing carefully and limiting applications helps protect your score and your budget at the same time.
📌 Key Takeaway: Small, consistent actions—like automatic payments and focused payoff plans—often matter more than dramatic one-time moves when it comes to rebuilding your credit score.
Using Secured Cards and Starter Products Wisely
If your credit score has dropped significantly, traditional credit cards or loans may be hard to qualify for. That is where secured cards and other starter products can play a role in credit rebuilding. A secured card typically requires a cash deposit that becomes your credit limit. You then use the card like any other, making purchases and payments, and your activity is reported to the credit bureaus. Over time, responsible use can help rebuild your credit history and demonstrate reliability to future lenders.
For Veterans, the key is to treat these tools as stepping stones rather than new sources of long-term debt. A secured card can be powerful when used for small, planned expenses—such as a monthly subscription or gas—and paid off in full each month. This pattern builds a positive payment history without adding financial strain. It can also be helpful to confirm that the card reports to all major credit bureaus; otherwise, your efforts may not show up where they matter most for your credit score.
Making Room in Your Budget Without Punishing Yourself
Debt management and credit rebuilding both depend on having some room in your budget to make progress. That does not mean cutting everything that brings you comfort or joy, especially when you are already carrying the weight of past experiences. Instead, it means looking honestly at where your money goes and choosing, with intention, where you want it to go next. This is less about self-denial and more about aligning your spending with what actually matters to you now, not what mattered during a different season of life.
Some Veterans find it helpful to divide expenses into three broad categories: essentials, obligations, and choices. Essentials are things like housing, food, utilities, and basic transportation. Obligations include minimum debt payments and any legal or contractual commitments. Choices are everything else—from streaming services to dining out to impulse purchases. Even small adjustments in the “choices” category can free up money to put toward debt or savings. The goal is not perfection; the goal is to create enough breathing room that progress on your credit rebuilding plan feels possible, not punishing.
💡 Pro Tip: If budgeting feels overwhelming, start with just one change—such as limiting takeout to specific days or canceling one unused subscription—and direct that money toward a specific debt or savings goal.
Protecting Your Progress During Ongoing Challenges
Rebuilding credit after financial hardship is rarely a straight line. Life continues to happen: medical issues, job changes, family emergencies, and other unexpected events can disrupt even the best plans. For Veterans, ongoing health treatment, disability claims, or shifts in benefits can add extra layers of uncertainty. That is why it helps to think of your credit rebuilding plan as something flexible, not fragile. The goal is to protect your progress when possible and adjust your approach when necessary, rather than abandoning it at the first setback.
One way to protect your progress is to build a small emergency buffer, even if it feels like you can only spare a little each month. A modest savings cushion can keep you from turning to high-interest credit in a crisis, which in turn helps keep your utilization lower and your payment history cleaner. Another way is to communicate early with creditors if you see trouble coming. Many lenders offer hardship programs, payment arrangements, or temporary relief options. These conversations are not always easy, but reaching out before you are in full crisis can sometimes prevent missed payments and additional damage to your credit report.
Connecting Credit Rebuilding to Overall Financial Wellness
Credit scores and debt balances are important, but they are only pieces of a larger picture: your overall financial wellness. For Veterans, financial wellness is closely tied to stability, independence, and the ability to make choices that align with your values and goals. Rebuilding credit is not just about getting approved for a loan; it is about having more control over where you live, how you travel, and what kind of future you can build for yourself and those you care about. It is also about reducing the daily stress that comes from feeling like money is always working against you.
As you work on debt management and credit rebuilding, it may help to think in terms of small, interconnected habits: checking your accounts regularly, setting aside a bit of savings when possible, saying no to new debt that does not serve your long-term goals, and seeking support when you need it. Over time, these habits can shift your financial life from reactive to proactive. That shift is at the heart of financial wellness—feeling that your money decisions are supporting you rather than constantly pulling you into the past.
📌 Key Takeaway: A healthier credit profile is not an end in itself; it is a tool that makes other parts of your life more stable, flexible, and aligned with what matters to you.
Emotional Weight, Self-Respect, and Moving Forward
Money problems can carry a heavy emotional weight. Many Veterans describe feeling embarrassed, angry, or defeated when they look at their credit reports or open collection letters. It is easy to confuse financial hardship with personal failure, especially if you are used to being the one others rely on. Yet your credit score does not reflect your service, your sacrifice, or your worth as a person. It is simply a snapshot of how certain financial events have been recorded over time. That snapshot can change, and you have the right to work toward a different picture—one step at a time.
Credit rebuilding for Veterans is not about perfection. It is about choosing, again and again, to act in your own best interest even when the process feels slow. It is about asking for help when you need it, whether from a counselor, a trusted friend, or a professional advisor. It is about recognizing that you have already navigated complex, high-pressure situations in your service, and those same qualities—persistence, focus, and adaptability—can support you in building a more stable financial future. Every on-time payment, every reduced balance, and every informed decision is a quiet way of honoring the life you are working to create now.
Bringing It All Together: A Practical Path for Veterans
Rebuilding credit after financial hardship does not happen overnight, but it also does not require impossible sacrifices or constant stress. For Veterans, a practical path often includes a handful of key moves: understanding how credit works, getting a clear picture of current debts, choosing a debt management strategy, using starter products like secured cards carefully, protecting progress during challenges, and connecting daily choices to broader financial wellness. None of these steps are flashy, but together they form a steady route from uncertainty toward greater security and choice.
Review your credit reports and correct any errors, especially those related to moves, deployments, or benefit changes.
List your debts, choose a snowball or avalanche approach, and make a simple plan you can track each month.
Consider a secured card or similar product as a tool for positive payment history, not as extra spending power.
Automate payments when possible, and communicate early with creditors if you anticipate trouble making a payment.
Build even a small emergency buffer to reduce reliance on high-interest credit when life throws something unexpected your way.
Each of these steps respects the reality that financial hardship is complex and that Veterans are often carrying more than numbers on a page. Credit rebuilding is not about erasing your past; it is about giving your future more room to breathe. Over time, as your credit score improves and your debts become more manageable, everyday tasks like renting, financing, or planning ahead begin to feel less like obstacles and more like options. That shift—from feeling trapped to feeling capable—is at the heart of financial wellness, and it is well within reach, one deliberate choice at a time.
📌 Ready for Support? If you’d like help turning these steps into a plan that fits your real life, you don’t have to do it alone. Click here to learn about one‑on‑one financial coaching tailored for Veterans and their families.