Veterans' Guide to Stress-Free Budgeting
Personal Finance, Veterans Budgeting, Money Management
How Veterans Can Track Spending Without Feeling Restricted
Tracking your money does not have to feel like being back on a strict schedule or under someone else’s command. For many veterans, the idea of “budgeting” sounds like limitation, when what you really want is financial freedom, stability, and room to breathe. This guide explores how veterans can use a simple spending tracker and practical budgeting tips to manage money with more ease and less pressure.
Why Traditional Budgeting Often Feels Wrong for Veterans
Many veterans are used to operating under clear rules, orders, and structure. Ironically, that can make traditional budgeting feel like a step backward rather than progress. A rigid spreadsheet that tells you exactly how much you’re “allowed” to spend in each category can feel like another chain of command breathing down your neck. Money becomes one more area where you feel watched, judged, or boxed in.
Effective veterans budgeting does not have to look like that. Instead of focusing on restriction, you can focus on awareness. A spending plan that works for you should:
Respect your independence and decision-making
Acknowledge the realities of VA benefits, disability pay, or retirement income
Give you options instead of orders
When you reframe money management as a way to create choices instead of limits, tracking your spending becomes less about “no” and more about “what do I want my money to do for me?”
📌 Key Takeaway: Budgeting for veterans works best when it is about clarity and control, not punishment or perfection.
Start with Your Mission: What Does Financial Freedom Mean to You?
In service, every operation had a mission. You knew why you were doing something, not just what you were doing. The same approach can transform your personal finances. Before you even open a spending tracker app or pick up a notebook, take a moment to define your mission for financial freedom.
For one veteran, financial freedom might mean being able to cover all monthly expenses without worrying when the next check hits. For another, it might mean paying off high-interest credit cards or saving for a reliable truck. Someone else might want the ability to move closer to family or go back to school without debt hanging overhead. Your mission is personal, and it does not have to impress anyone else.
Short-term mission: “I want to stop overdrafting my account.”
Mid-term mission: “I want $1,000 in savings so emergencies don’t wreck me.”
Long-term mission: “I want to retire comfortably without worrying about each bill.”
Once you have a mission, veterans budgeting becomes a tool to support that mission, not a rulebook to follow blindly. Every choice with your money can be measured against a simple question: “Does this move me closer to or further from my mission?”
Awareness First, Rules Later: The Gentle Way to Track Spending
One of the biggest mistakes people make with money management is trying to jump straight into strict rules before they even understand where their money is going. It is like trying to fix a vehicle without first checking what is actually wrong. A better approach, especially if you hate feeling restricted, is to focus on awareness first and structure later.
Step 1: Choose a Simple Spending Tracker That Fits Your Style
A spending tracker does not need to be complicated. You can use:
A notes app on your phone where you jot down purchases
A basic spreadsheet with columns for date, amount, and category
A dedicated budgeting or spending tracker app that connects to your bank (many are free or low cost)
The best tool is the one you will actually use. If you like pen and paper, there is nothing wrong with a notebook. If you prefer your phone, go with that. The goal is not to create a perfect system; it is to get a clear picture of where your money goes each week.
Step 2: Track Without Judging Yourself for 30 Days
For the first month, give yourself permission not to change anything. Just watch. Every time you spend, record it. Groceries, fast food, gas, streaming services, that extra coffee—everything. This is not about shame; it is about data. You are gathering intel on your own habits so you can make informed decisions later.
💡 Pro Tip: Set a daily reminder on your phone to update your spending tracker. Two minutes a day beats an hour of trying to remember everything at the end of the week.
Step 3: Look for Patterns, Not Problems
After 30 days, sit down with your notes or app and look for patterns. You might notice you spend more on takeout on days you feel stressed or lonely. Maybe weekends are when most of the “mystery” spending happens. Perhaps subscriptions you forgot about are quietly draining your account each month. These are not failures; they are clues.
This awareness is the foundation of effective veterans budgeting. Instead of someone else telling you where you “should” cut back, you get to decide which patterns fit your mission for financial freedom and which ones are holding you back.
Building a Flexible Veterans Budget That Leaves Room to Breathe
Once you understand your spending patterns, you can start shaping a budget that supports your life instead of squeezing it. A flexible budget is less about exact dollar amounts and more about priorities. It recognizes that some months include unexpected travel, medical costs, or family needs. It also respects that enjoyment—coffee with a friend, a fishing trip, a movie night—matters just as much as bills and debts.
The Three-Category Method: Needs, Goals, Enjoyment
One simple budgeting tip for veterans who dislike rigid rules is to break spending into three broad categories instead of twenty tiny ones:
Needs: Housing, utilities, food, transportation, insurance, basic medical costs, minimum debt payments
Goals: Savings, extra debt payments, education, business ideas, moving funds toward your definition of financial freedom
Enjoyment: Dining out, hobbies, travel, gifts, entertainment, anything that makes life feel more like living and less like surviving
Using your spending tracker data, estimate how much of your monthly income currently goes to each of these categories. Then, gently adjust the percentages to better match your mission. Maybe you aim for:
60% Needs
20% Goals
20% Enjoyment
These numbers are not laws; they are guidelines. Some months you might spend more on needs and less on enjoyment, and that is fine. The point is to see clearly where your money goes and to make intentional choices rather than reacting to every bill and impulse purchase.
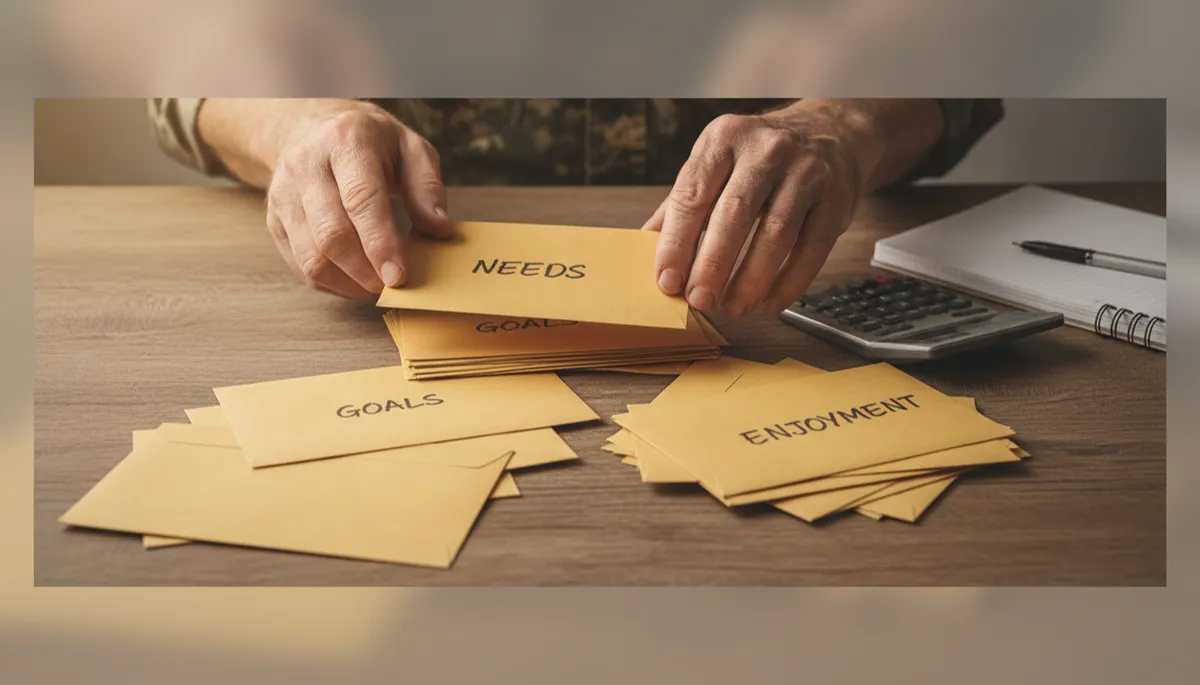
Separating money into broad categories turns budgeting into a simple, repeatable routine.
Give Every Dollar a Job—But Leave a Little Unassigned
A popular money management idea is to “give every dollar a job.” That means you decide in advance where each dollar of income will go—rent, groceries, gas, savings, and so on. For veterans who dislike strict control, this can feel tight, but there is a way to soften it: build in a “flex” category.
After you assign money to your needs and goals, set aside a small amount that is unassigned on purpose. Call it “flex,” “freedom,” or simply “whatever.” This pool gives you room to say yes to a last-minute invite or handle a minor surprise without feeling like you broke your budget. You are still practicing strong veterans budgeting, but you are doing it in a way that respects real life.
Practical Budgeting Tips Tailored for Veterans’ Realities
Veterans face unique financial situations: disability ratings that may change, retirement pay, reserve or Guard income, part-time work, or periods of unemployment while transitioning. Here are some budgeting tips designed with those realities in mind.
1. Build Your Budget Around Your Most Reliable Income
If you receive VA disability, retirement pay, or another consistent benefit, use that as the backbone of your budget. Cover your core “Needs” category with the income you can count on every month. Then, treat any additional income—from part-time work, gigs, or overtime—as bonus money you can direct toward “Goals” and “Enjoyment.”
2. Automate the Boring Parts of Money Management
Automation can be a powerful ally in veterans budgeting. Set up automatic payments for fixed bills like rent, utilities, and insurance. Consider automatic transfers to savings on payday, even if it is just a small amount. When the essentials are handled in the background, your spending tracker can focus on the areas where you truly have choices, like food, entertainment, and extras.
3. Create a “Calm Money” Fund for Tough Days
Life after service can include days when stress, pain, or mental health challenges make everything feel heavier—including money decisions. One supportive budgeting tip is to set aside a small “calm money” fund. This is separate from your emergency savings. It is a small amount—maybe $20–$50 a month—reserved for whatever genuinely helps you get through a hard day without blowing your whole budget: takeout, a ride-share instead of driving, a streaming rental, or a quiet coffee out of the house.
Knowing this fund exists can reduce the urge to completely ignore your spending tracker when things feel overwhelming. You are not failing your money management plan by using it; you are following it.
4. Use the “One Change at a Time” Rule
When you start seeing your spending patterns, it can be tempting to try to fix everything at once. That is how burnout happens. Instead, commit to changing just one thing at a time. Maybe you decide to cut your takeout spending by $40 a month and move that money into your “Goals” category. Once that feels normal, choose another area to adjust. Slow changes stick better than sudden, extreme ones.
5. Check In Weekly, Not Constantly
You do not need to stare at your account every day to have strong money management. In fact, constantly checking can increase anxiety. Instead, schedule a weekly “money check-in.” Spend 15–20 minutes reviewing your spending tracker, updating any cash purchases, and comparing your actual spending to your three categories: Needs, Goals, Enjoyment. Ask yourself:
What went well this week with my money?
What surprised me?
Is there one small adjustment I want to make for next week?
📌 Key Takeaway: Consistency beats intensity. A calm weekly review does more for financial freedom than a single stressful overhaul.
Turning Tracking into Freedom, Not Surveillance
If tracking your spending brings up feelings of being watched, controlled, or evaluated, you are not alone. Many veterans connect record-keeping with inspections, evaluations, and consequences. To make veterans budgeting feel different, it helps to change the story you tell yourself about what tracking means.
You Are the Commander of Your Money
In the military, good leaders rely on accurate information. They do not track details to punish their team; they track so they can make better decisions, keep people safe, and accomplish the mission. Your spending tracker can serve the same purpose. It is not your boss—it is your briefing. It gives you the intel you need to decide how to move toward financial freedom with the resources you have right now.
Progress, Not Perfection, Is the Measure of Success
There will be months when everything goes off plan: a car repair, a family emergency, a stretch of unemployment, or simply a run of days when you choose convenience over savings. That does not mean your money management has failed. It means you are human and your life is real. The key is to keep coming back to your tools—your spending tracker, your three categories, your mission—without shame.
Each time you notice a pattern and adjust it, you are practicing veterans budgeting in a way that respects your experience and your goals. Over time, those small adjustments add up to meaningful financial freedom: fewer surprises, more choices, and less stress when you open your bank app.
When to Ask for Backup: Support and Resources for Veterans
Even the best tools cannot replace support. If you feel stuck, overwhelmed, or unsure where to start, it is completely reasonable to ask for backup. Just like you would not hesitate to call in support on a mission, you do not have to navigate money management alone.
Veterans Service Organizations (VSOs): Many offer free or low-cost financial education and counseling tailored to veterans’ situations.
Nonprofit Credit Counselors: Reputable agencies can help you review debts, create a realistic plan, and even negotiate with creditors if needed.
Peer Support: Talking with other veterans who are working toward financial freedom can make the process feel less isolating and more achievable.
Asking for help is not a sign that you mismanaged your money. It is a sign that you are serious about your future and willing to use every tool available to you—including people who understand the terrain.
Bringing It All Together: A Veteran-Friendly Path to Financial Freedom
Tracking your spending does not have to feel like another inspection or another set of orders. When you place your mission at the center—your personal definition of financial freedom—and choose tools that respect your independence, veterans budgeting becomes something different. It becomes a way to honor your hard work, your service, and your future.
A simple spending tracker, used without judgment, gives you clear information about your habits. Broad categories like Needs, Goals, and Enjoyment keep your money management flexible and realistic. Gentle budgeting tips—like automating bills, setting up a “calm money” fund, and making one change at a time—help you move forward without feeling restricted or overwhelmed.
Over time, these small, steady choices can shift your financial life in powerful ways. Bills feel less like ambushes. Savings starts to grow. Debts begin to shrink. Most importantly, your money starts to support the life you want now, not just the life you had before. That is financial freedom in action: not perfection, but progress you can feel and measure, one month at a time.
You have already navigated complex systems, high-pressure situations, and major transitions. Compared to that, learning to track your spending and shape a veteran-friendly budget is a mission well within your reach. Start small, stay curious, and let your spending tracker be a quiet ally on your path toward the financial freedom you deserve.
📣 Ready for One-on-One Support? If you want help turning these ideas into a plan that fits your real life, you don’t have to do it alone. Click here to learn about veteran-friendly financial coaching and get personalized guidance on your next steps.