VA Home Loan Prep: Financial Coaching Tips
VA Home Loan, Financial Coaching, Home Loan Preparation, Veteran Benefits, Mortgage Tips, Loan Application Guide
VA Home Loan Financial Coaching: How to Prepare Before You Apply
A VA Home Loan can be one of the most powerful Veteran benefits you’ll ever use—but only if you walk into the process prepared. Think of this as your calm, practical coaching session before you sit down with a lender, so your first conversation starts on your terms, not theirs.
Why Preparation Matters Before a VA Home Loan
The VA Home Loan program is designed to honor your service by making homeownership more accessible. No down payment in many cases, no private mortgage insurance, and competitive interest rates are powerful advantages. Yet those benefits don’t automatically guarantee a smooth experience or a smart long-term decision. That’s where intentional home loan preparation and thoughtful financial coaching come in.
A coach doesn’t just cheer from the sidelines. They help you build a plan, anticipate obstacles, and move with purpose. Applied to your VA Home Loan, financial coaching means getting clear on your numbers, your goals, and your limits before any lender pulls your credit or shows you a rate sheet. It’s the difference between reacting to offers and confidently choosing what truly fits your life.
Step 1: Understand the Core VA Home Loan Benefits
Before you dive into numbers, it helps to know exactly what makes a VA Home Loan different from a conventional mortgage. When you understand your Veteran benefits, you can use them strategically instead of just accepting whatever a lender suggests. Here are the foundational advantages many eligible borrowers can access:
No down payment in many cases: You may be able to finance up to 100% of the home’s value, preserving your savings for moving costs, repairs, and emergencies.
No private mortgage insurance (PMI): Conventional loans often require PMI when you put less than 20% down. With a VA Home Loan, this ongoing monthly fee is usually not required, lowering your overall payment.
Competitive interest rates: Because the VA backs a portion of the loan, lenders often offer more favorable rates than many non-VA options for similarly qualified borrowers.
Flexible credit guidelines: The VA itself doesn’t set a strict minimum credit score, though individual lenders do. Still, VA loans can be more forgiving than some conventional programs.
Limits on certain closing costs: The VA restricts some fees lenders can charge, offering another layer of protection for you as the borrower.
These Veteran benefits are powerful, but they’re not a blank check. You still need to qualify based on income, credit, and overall financial stability. Thoughtful financial coaching helps you line up those pieces before you ever fill out a loan application.
Step 2: Treat Financial Coaching as Your Pre-Game Strategy Session
Financial coaching isn’t about being lectured. It’s about having a structured conversation that puts you in control. Whether you work with a nonprofit counselor, a base financial readiness program, or an independent coach who understands VA loans, the goal is the same: to help you see the full picture before you commit to a long-term mortgage.
In a coaching session focused on VA Home Loan preparation, you might walk through:
Your current income streams, including military pay, VA disability compensation, pensions, or civilian employment.
Existing debts—credit cards, auto loans, student loans, personal loans—and how they affect your borrowing power.
Monthly living expenses, from groceries and gas to childcare and medical costs, to see what mortgage payment truly fits your life.
Your savings habits and emergency fund, so you’re not house-rich but cash-poor when something unexpected happens.
📌 Key Takeaway: A great financial coach doesn’t just tell you what you qualify for—they help you define what you’re comfortable with, even if that number is lower than what a lender might approve.
Step 3: Clarify Your Homeownership Goals Before You Run the Numbers
Not every home purchase has the same purpose. Some people want a long-term family home; others are looking at a starter house, a property near a duty station, or even a place they plan to convert into a rental later. Your goals shape the type of VA Home Loan that makes sense and the financial coaching you need along the way.
Ask yourself questions like:
How long do I realistically plan to live in this home—three years, ten years, longer?
Am I comfortable with potential moves due to PCS orders or job changes, and how would that affect this purchase?
Do I want a payment that leaves room for travel, hobbies, and savings, or am I willing to stretch for a higher price point?
Is this my “forever home,” or is it a stepping stone toward something else?
Clear goals help you and your coach build a loan application guide that’s tailored to your situation, not just a generic checklist. They also keep you grounded when you’re browsing listings or being shown homes at the top of your budget.
Step 4: Get Real About Your Budget—Not Just What a Lender Says
One of the most practical pieces of financial coaching is building a realistic, line-by-line budget that includes your future mortgage payment. A lender might tell you that you’re approved for a certain amount, but that doesn’t mean living at that payment level will feel comfortable or sustainable for you and your family.
Start with your current monthly take-home pay. Then map out your recurring obligations:
Housing-related costs you already have (rent, utilities, renter’s insurance) and what might change when you own a home (property taxes, homeowner’s insurance, higher utilities, HOA dues).
Transportation expenses, including car payments, insurance, fuel, and maintenance, especially if your new home changes your commute.
Food, healthcare, childcare, and other essentials that don’t go away when you sign a mortgage.
Savings goals, including retirement, emergency funds, and any future plans like education or starting a business.
💡 Mortgage Tip: Try “test-driving” your future payment. For three to six months, set aside the difference between your current housing cost and your projected VA Home Loan payment in a separate savings account. If that feels tight, it’s a signal to adjust your target price range.
Step 5: Strengthen Your Credit Profile Before You Apply
Your credit doesn’t have to be perfect to qualify for a VA Home Loan, but a stronger profile can unlock better interest rates and smoother approvals. Effective home loan preparation includes a deliberate review of your credit well before you submit a formal application.
As part of your personalized loan application guide, consider these credit-focused steps:
Pull your credit reports from all three major bureaus and review them for accuracy. Dispute errors well in advance, since corrections can take time to process.
Lower revolving balances on credit cards if possible. Reducing your utilization ratio—how much of your available credit you’re using—can positively influence your score.
Avoid opening new lines of credit right before you apply. New accounts and hard inquiries can temporarily lower your score and complicate underwriting.
Stay current on all payments. A single late payment close to your application date can raise questions, even if your overall history is strong.
A financial coach can help you prioritize which actions will have the most impact in the time frame you’re working with. Sometimes that means delaying your application by a few months to put yourself in a stronger position—and that patience can pay off over the life of the loan.
Step 6: Organize Your Documentation Like a Pro
One of the most practical parts of any loan application guide is a clear document checklist. Having your paperwork ready doesn’t just make your lender’s life easier; it also shortens timelines and reduces stress for you. For a VA Home Loan, you’ll typically need:
Certificate of Eligibility (COE): This confirms to the lender that you qualify for VA loan benefits based on your service history or that of an eligible spouse.
Proof of service: Such as DD214 for Veterans, a statement of service for active-duty members, or other relevant documentation as directed by the VA or your lender.
Income verification: Recent pay stubs, W-2 forms, tax returns, and documentation for any additional income like disability compensation, pensions, or side work.
Asset statements: Bank statements, retirement accounts, and any other savings or investment accounts that demonstrate your financial stability and reserves.
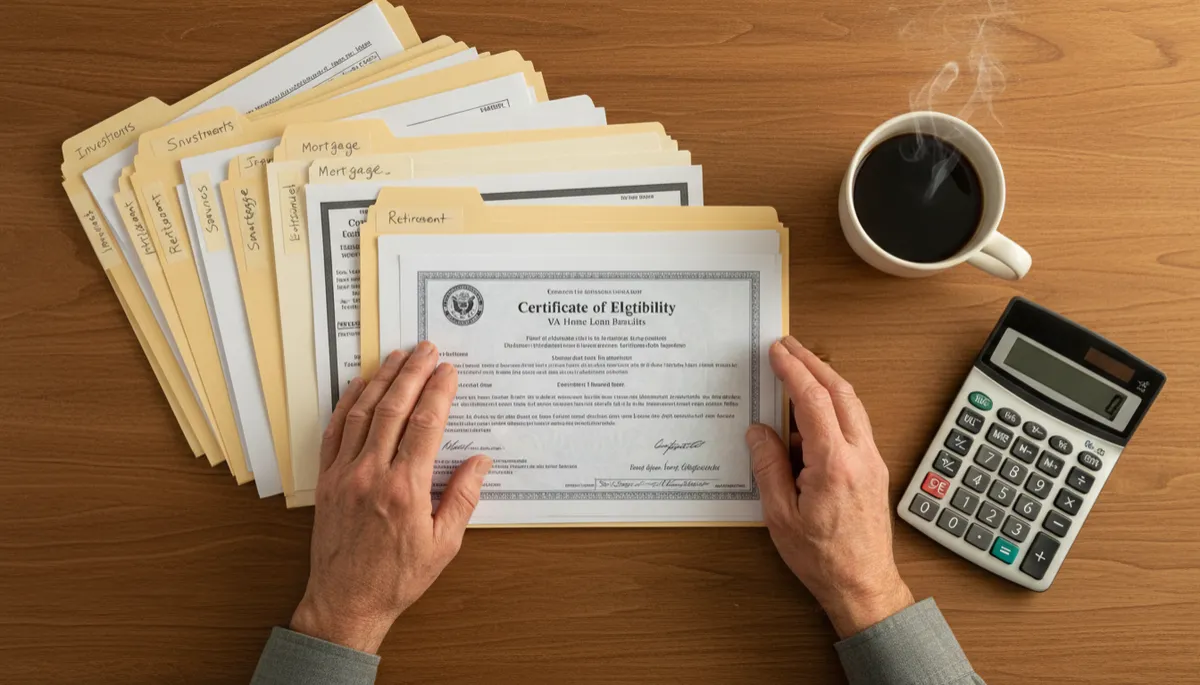
A simple, organized document folder can shave days off your loan approval timeline.
A financial coach can walk you through this list and help you build a secure digital folder or physical binder. That way, when your lender asks for something, you’re not scrambling—you’re ready to send it within minutes.
Step 7: Plan for Upfront and Ongoing Homeownership Costs
Even with the generous features of a VA Home Loan, there are real costs involved in both buying and owning a home. Mortgage tips that ignore these realities can leave you feeling blindsided later. Financial coaching helps you anticipate and plan for these expenses instead of being surprised by them.
Upfront Costs to Consider
Earnest money deposit: A good-faith deposit you make when you submit an offer on a home, often credited back to you at closing if the deal goes through.
Appraisal and inspection fees: These protect you and the lender by confirming the property’s value and condition, but they are typically paid out of pocket during the process.
VA funding fee (if applicable): Many borrowers pay a one-time funding fee, which can often be rolled into the loan. Certain Veterans with service-connected disabilities and some surviving spouses may be exempt.
Ongoing Costs After Closing
Maintenance and repairs: From a leaky faucet to replacing a roof years down the line, homeowners are their own landlords. Setting aside a maintenance fund is part of smart home loan preparation.
Property taxes and insurance: These may be included in your monthly mortgage payment through an escrow account, but the amounts can change over time as local tax rates and insurance premiums shift.
Utilities and HOA fees: Larger homes or different locations can bring higher utility costs, and some neighborhoods charge homeowner association dues for shared services and amenities.
📌 Key Takeaway: A VA Home Loan can reduce how much cash you need to get into a home, but it doesn’t remove the responsibility of ongoing ownership. Planning for those costs is part of honoring your own financial well-being.
Step 8: Learn How Lenders Evaluate Your Application
Another valuable element of financial coaching is demystifying how lenders look at your VA Home Loan application. Understanding their perspective doesn’t mean you have to agree with every recommendation, but it does help you prepare strategically and ask better questions.
In general, lenders will focus on:
Debt-to-income ratio (DTI): The percentage of your gross monthly income that goes toward debt payments. A lower DTI suggests more breathing room in your budget and can support approval.
Residual income: Unique to VA loans, this calculation considers how much income you have left after debts and expenses. It’s designed to ensure you can comfortably afford basic living costs after paying your mortgage.
Credit history and patterns: Beyond the score itself, underwriters look at the story your credit tells—consistent payments, any past delinquencies, and how you’ve managed debt over time.
A coach who understands VA guidelines can help you interpret these standards and identify where you’re strong and where you may want to improve before you apply. That insight turns a mysterious process into a manageable one.
Step 9: Use Mortgage Tips to Protect Yourself During the Search
Once your financial coaching work has given you a solid foundation, you’ll likely move into the preapproval and home-search phase. This is where practical mortgage tips can help you stay grounded amid excitement, sales pressure, and fast-moving markets.
Shop lenders, not just houses: Different lenders can offer different rates, fees, and levels of experience with VA Home Loans. Comparing at least a few options can save you money over time and reduce frustration during underwriting.
Work with a VA-savvy real estate agent: An agent familiar with Veteran benefits and VA appraisal requirements can help you avoid properties that are unlikely to meet standards or that could cause delays.
Stay honest about your comfort zone: If a lender or agent encourages you to “stretch” beyond the budget you set with your financial coach, remember that you’re the one who will live with the payment, not them.
💡 Mortgage Tip: When comparing offers, look beyond the interest rate. Ask for a standardized loan estimate so you can see fees, projected monthly payments, and total costs over time in a side-by-side format.
Step 10: Build a Long-Term Plan for Your VA Home Loan
A VA Home Loan isn’t just a transaction; it’s a long-term commitment that can support broader financial goals when used intentionally. The same financial coaching that prepares you to apply can also help you map out what comes next—how this loan fits into your bigger picture over five, ten, or twenty years.
Together with a coach, you might explore:
Strategies for paying down principal faster if your budget allows, potentially saving thousands in interest over the life of the loan.
How future changes—like retirement from service, a civilian career shift, or family size changes—might influence your housing needs and whether refinancing could make sense down the line.
The role of your home within your broader financial plan, including building equity, protecting against housing inflation, and maintaining flexibility for future moves.
When you look at your VA Home Loan through this wider lens, it becomes more than a monthly payment. It becomes a tool you’re using intentionally, backed by the Veteran benefits you’ve earned and the preparation you’ve put in.
Putting It All Together: A Calm, Practical Path to Your VA Home Loan
Preparation doesn’t remove every unknown from the homebuying process, but it does change your posture. Instead of reacting to every new document request or number on a screen, you move through each step with a clearer sense of what you want and what you’re willing to accept. Financial coaching gives structure to that preparation, turning loose ideas into a concrete home loan preparation plan you can actually follow.
As you consider your next move, you might think of this guide as a starting point for your own personalized plan:
Get familiar with your VA Home Loan benefits so you know what’s available to you, not just what’s offered in a single conversation.
Sit down—on your own or with a coach—and map out your income, expenses, and goals in honest detail.
Strengthen your credit and organize your documents before you reach out to lenders, so you’re presenting your best self from day one.
Use mortgage tips and your own comfort zone to filter offers and advice, remembering that the right loan is one that fits your life, not just your approval amount.
You’ve already done the hard work of earning your Veteran benefits. Taking time for thoughtful financial coaching and deliberate home loan preparation is a way of honoring that effort—and protecting your future. When you’re ready to apply, you won’t be stepping into the unknown. You’ll be walking into a conversation you’ve already prepared yourself to lead.
Ready for one-on-one support?Click here to schedule your VA-focused financial coaching session and turn this guide into a personalized action plan.