VA Home Loan Prep: Financial Coaching Tips
VA Home Loan, Financial Coaching, Home Loan Preparation, Veteran Benefits, Mortgage Tips, Loan Application Guide
VA Home Loan Financial Coaching: How to Prepare Before You Apply
Owning a home can feel like a powerful next chapter after military service. Yet even with the support of a VA Home Loan, the process can seem complicated, full of paperwork, numbers, and decisions that carry long-term consequences. Financial coaching bridges the gap between your goals and the realities of home loan preparation, helping you approach your loan application with clarity instead of guesswork.
Why Preparation Matters Before a VA Home Loan Application
The VA Home Loan program is one of the most valuable veteran benefits available. No down payment in many cases, competitive interest rates, and no private mortgage insurance can make homeownership more accessible than with a conventional mortgage. Still, those advantages do not replace the need for thoughtful home loan preparation. A loan is a long-term commitment, and the decisions you make now will shape your financial life for years to come.
Financial coaching offers a structured way to prepare. Instead of rushing into a pre-approval and hoping everything works out, you slow down just enough to understand your numbers, your options, and your limits. That preparation can mean the difference between a home that supports your life and a mortgage that quietly strains it month after month.
Understanding the VA Home Loan: The Foundation of Smart Choices
Before you can prepare effectively, it helps to understand what the VA Home Loan actually offers and what it does not. A coach will often begin here, making sure you are clear on the basics so later decisions feel grounded instead of rushed or confusing.
No down payment in many cases: This is one of the best-known features. You may be able to buy with 0% down, but that does not automatically mean you should stretch to the highest price you can qualify for.
No private mortgage insurance (PMI): Skipping PMI can save you a significant amount each month compared with some conventional loans, freeing up room in your budget for other priorities or future savings.
Competitive interest rates: Because of the VA guarantee to lenders, interest rates are often lower than comparable non-VA loans, which can reduce your total cost of borrowing over time.
Funding fee: Most borrowers pay a VA funding fee, which can be rolled into the loan. This cost is easy to overlook, and a coach will help you understand how it affects your total loan amount and monthly payment.
These features are powerful, but they work best when matched with a clear plan. Financial coaching encourages you to move beyond “Can I get approved?” and toward “Does this loan support my long-term stability and goals?”
What Financial Coaching Looks Like for VA Home Loan Preparation
Financial coaching is different from sales, and it is different from traditional financial advice. Instead of pushing a product or managing your investments, a coach focuses on your behavior, your decisions, and your day-to-day money habits. In the context of a VA Home Loan, that means working through the numbers and choices that shape your readiness to buy a home and maintain it comfortably.
During coaching sessions, you might review your income and expenses line by line, talk through past money experiences, and explore what “affordable” really means for your life. The coach is there to ask questions you may not have considered, highlight blind spots, and help you build a plan that feels realistic, not just optimistic. When you eventually sit down with a lender, you are not starting from zero—you are arriving with a clear sense of what you want and what you can handle.
📌 Key Takeaway: Financial coaching is not about telling you “yes” or “no” on a home purchase. It is about equipping you with the information and confidence to make that decision for yourself, using your VA Home Loan as a tool rather than a temptation.
Step 1: Clarify Your Why Before You Clarify Your Numbers
Many loan conversations jump straight into credit scores and interest rates. Coaching often starts a step earlier: Why do you want to buy a home right now? The answer shapes almost every other decision in your loan application guide and home loan preparation journey.
Are you looking for stability for your family after frequent moves?
Do you want to build equity instead of paying rent to someone else?
Are you hoping for a property that could later become a rental?
Are you transitioning from active duty and unsure where you will live long term?
When your reasons are clear, decisions about location, price range, and timing become easier to evaluate. A home that makes sense for a long-term, settled lifestyle might not be the right fit if your career or family situation is still in motion. Financial coaching keeps your “why” in view, so the numbers you choose later are anchored to a purpose, not just a pre-approval amount.
Step 2: Build a Realistic Budget Around Life, Not Just the Mortgage
One of the most practical parts of financial coaching is turning abstract affordability into a clear monthly picture. A lender may approve you for a certain payment, but that payment exists inside your real life—groceries, gas, childcare, health care, and the unexpected repairs that seem to appear exactly when they are least convenient.
Together with a coach, you lay out your current income, including basic pay, disability compensation, retirement income, or civilian salary. Then you map out your regular expenses and obligations. This exercise is not about judgment; it is about visibility. Once everything is on the table, you can ask a more useful question than “What will a lender give me?” Instead, you ask, “What mortgage payment fits comfortably within this life I am actually living?”
💡 Mortgage Tip: When planning with your coach, consider not only the principal and interest but also property taxes, homeowner’s insurance, potential HOA dues, and a monthly amount set aside for repairs. This fuller number is the real cost of homeownership.
Step 3: Strengthen Your Credit Profile With Intention
The VA does not set a minimum credit score for VA Home Loan eligibility, but lenders do. Those lender requirements can vary, and stronger credit often opens doors to better terms. Financial coaching helps you understand your credit report, not just your score, and identify practical steps you can take before you apply.
Reviewing your credit reports from all three major bureaus and disputing clear errors.
Creating a plan to reduce high-interest balances that raise your utilization ratio.
Setting up automatic payments or reminders to avoid late payments that drag scores down.
Choosing whether to pay off certain debts now or keep more cash on hand for closing costs and reserves.
Instead of guessing which actions matter most, you work with your coach to prioritize moves that can make a meaningful difference within your timeline. That might mean delaying your application by a few months to clean up your profile, or it might mean focusing on stability and on-time payments rather than drastic changes. Either way, your choices are deliberate, not random.
Step 4: Manage Existing Debt Before Adding a Mortgage
Your debt-to-income (DTI) ratio is one of the key numbers in any loan application guide. Even though the VA is often more flexible than conventional programs, your existing debts still shape how much home you can qualify for and how comfortable your monthly life feels afterward. Financial coaching creates space to look at your debt with honesty and strategy rather than shame or avoidance.
Together, you might explore different approaches: paying down high-interest credit cards, consolidating certain balances, or simply freezing additional borrowing while you prepare. The goal is not perfection; it is progress that supports your homeownership plan. A coach can also help you understand how certain debts, like auto loans or personal loans, will factor into a lender’s calculations so there are fewer surprises later in the process.
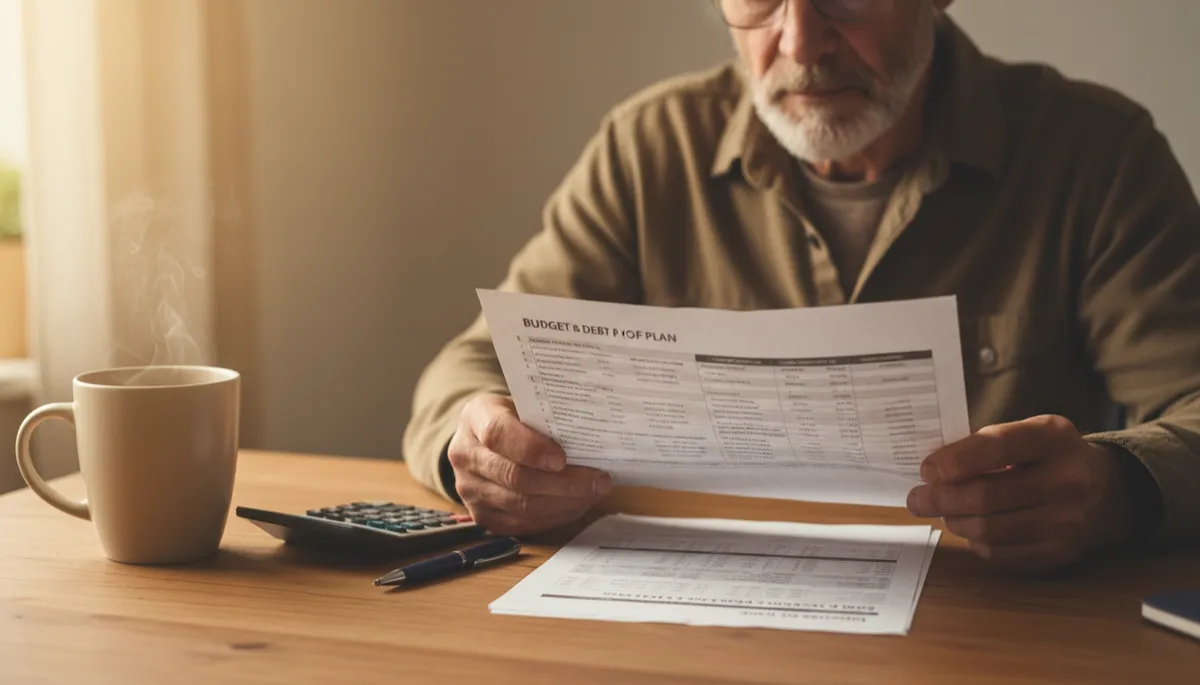
Close-up of a veteran reviewing a printed budget and debt payoff plan at a wooden desk, coffee...
Tackling key debts before applying can expand your options and lower stress.
Step 5: Use Your Veteran Benefits Intentionally, Not Automatically
Your service has earned you access to a range of veteran benefits, and the VA Home Loan is one of the most visible. Financial coaching invites you to think of that benefit as part of a larger financial picture, not just a one-time opportunity you need to grab as quickly as possible. Sometimes, the best use of your benefit is to wait until your situation is more stable. Other times, acting sooner makes sense because of your family needs or local housing costs.
A coach can help you explore questions like whether to use your VA entitlement for a starter home or hold it for a longer-term property, how disability status might affect your funding fee, and what role other benefits—such as education, health care, or vocational support—play in your long-term financial resilience. The goal is not just to use the VA Home Loan, but to use it wisely within a broader life plan.
Step 6: Create a Savings Cushion That Supports Your New Home
One of the subtle risks of a zero-down VA Home Loan is the temptation to buy with almost no cash reserves. While the program allows low or no down payment, homeownership still comes with upfront and ongoing costs. Financial coaching treats savings as a central part of home loan preparation, not an optional extra you will figure out later.
Setting a target emergency fund to cover several months of living expenses.
Planning for closing costs, even if some are covered by the seller or lender.
Building a small “house fund” for immediate needs like minor repairs, furniture, or safety updates.
A coach helps you map out how much to set aside, how long it might take, and what trade-offs you are willing to make to reach those goals. Sometimes that means delaying your purchase by a few months; sometimes it means adjusting your target price range to leave room for savings. Either way, the decision is intentional and grounded in your actual numbers.
Step 7: Organize Your Documents So the Loan Application Feels Orderly
A practical but often overlooked part of any loan application guide is documentation. Lenders will ask for proof of income, assets, service history, and more. Scrambling to find these items at the last minute can add stress to an already emotional process. Financial coaching encourages you to prepare a simple system before you begin applying, so the paperwork feels manageable instead of overwhelming.
Recent pay stubs or proof of other income sources.
Bank statements and investment account summaries for the last few months.
Tax returns, especially if you are self-employed or have variable income.
Your Certificate of Eligibility (COE) for the VA Home Loan.
A coach can help you create a checklist and a simple folder system—digital, physical, or both—so when a lender asks for a document, you know exactly where to find it. That organization also signals to lenders that you are a prepared and serious borrower, which can help the process move more smoothly.
Step 8: Compare Lenders and Offers With a Clear Framework
Not all VA-approved lenders are the same. Interest rates, fees, communication style, and overall support can vary widely. Financial coaching gives you a framework for comparing offers so you are not swayed only by a single number or a polished sales pitch. Instead, you evaluate each option against the priorities you have already identified during your home loan preparation work.
💡 Mortgage Tip: When reviewing VA Home Loan offers, look beyond the interest rate. Compare annual percentage rates (APRs), total closing costs, estimated monthly payments, and whether there are prepayment penalties or other restrictions that could affect your flexibility later.
With a coach, you can walk through sample Loan Estimates and ask questions in a low-pressure setting. That way, when you talk with lenders directly, you already know which questions matter most to you and how to interpret the answers you receive. This is where coaching and a practical loan application guide work together: you bring both emotional clarity and technical understanding into the conversation.
Step 9: Prepare Emotionally for the Ups and Downs of the Process
Buying a home, especially with the help of a VA Home Loan, can stir up a mix of pride, anxiety, hope, and pressure. Financial coaching acknowledges that emotions are part of the process, not a distraction from it. A coach can help you anticipate the moments when stress tends to spike—like waiting for underwriting approval or negotiating repairs after an inspection—and plan how you want to respond.
This emotional preparation does not replace the technical side of mortgage tips and numbers, but it supports it. When you know that nerves are normal, you are less likely to make rushed decisions just to make the discomfort stop. Instead, you can pause, revisit your budget and goals, and move forward in a way that still feels aligned with the plan you built at the beginning of your home loan preparation journey.
How to Find Financial Coaching That Understands VA Home Loans
Not every financial professional is familiar with the details of VA Home Loan benefits. When you look for a coach, it helps to ask directly about their experience with veteran clients and VA-specific programs. You may find support through nonprofit organizations, veteran service groups, on-base resources, or independent coaches who specialize in working with military families and veterans.
Ask whether they understand the VA funding fee, eligibility requirements, and typical lender expectations for VA borrowers.
Look for a coaching approach that focuses on education and empowerment rather than selling specific financial products.
Notice whether they listen carefully to your goals and concerns instead of offering one-size-fits-all solutions.
When you find a good fit, that coaching relationship can extend beyond your home purchase. The same skills you build now—budgeting, planning, and navigating big financial decisions—will support you as you maintain your home, pay down your mortgage, and consider future choices like refinancing, renovations, or investing.
Pulling It All Together: A Practical Timeline for VA Home Loan Preparation
Every situation is unique, but it can help to see how these pieces might fit into a simple timeline. Think of this as a flexible guide rather than a rigid schedule, and adapt it with your coach based on your own starting point and priorities.
Three to six months before applying: Begin financial coaching, clarify your reasons for buying, review your budget, and pull your credit reports. Start any needed credit clean-up and set early savings goals.
Two to three months before applying: Organize your documents, refine your target price range based on your budget, and continue building your savings cushion. Talk with your coach about different lender options and what questions you plan to ask.
One month before applying: Narrow down your list of potential lenders, request initial information, and review sample estimates with your coach. Confirm that your budget, savings, and credit profile align with your goals.
During the application: Stay in touch with your coach as questions arise, revisit your budget if offers come in higher or lower than expected, and use your earlier preparation to stay grounded when decisions feel urgent.
This kind of timeline turns a vague intention—“I want to use my VA Home Loan someday”—into a series of manageable steps. Instead of reacting to deadlines and requests, you move through the process with a sense of direction and support.
Your Next Move: Turning Intention Into Action
A VA Home Loan can open doors, but it does not have to rush you through them. Financial coaching gives you room to pause, plan, and prepare so that when you do step forward, you do it with both eyes open. Instead of wondering whether you are missing something, you know you have taken the time to look at your income, your debts, your credit, your savings, and your reasons for buying a home—all through the lens of your unique life after service.
If you are considering a VA Home Loan, your next move does not have to be a loan application. It can be a conversation—with a financial coach, a trusted mentor, or a veteran-focused organization—that helps you see where you stand today and what steps would make you feel ready. From there, mortgage tips, loan application guides, and lender conversations become tools you use intentionally, not pressures you simply endure.
Your service has already involved planning, discipline, and resilience. Those same strengths can guide you through home loan preparation. With thoughtful financial coaching and a clear view of your veteran benefits, you can approach your VA Home Loan not as a gamble, but as a carefully considered step toward the kind of home life you want to build next.
✅ Ready for one-on-one support? Take the next step and explore personalized guidance tailored to your VA Home Loan journey. Click here to learn more about financial coaching options that can help you prepare with confidence.