Credit Score Basics for Veterans
Personal Finance, Veterans Finance, Credit Basics
Credit Score Basics for Veterans: What Matters Most
Your credit score can open doors to the benefits you have earned—or quietly hold you back. As a veteran, understanding how credit works is a powerful part of your financial toolkit, right alongside your VA benefits and hard-earned discipline. This guide walks through credit basics, what matters most for your score, and how to use Veterans Finance resources to build a stronger financial future.
Why Credit Scores Matter So Much for Veterans
A credit score is a three-digit snapshot of how you have handled borrowed money. Lenders use it to decide whether to approve you for credit cards, auto loans, mortgages, and sometimes even apartments or cell phone contracts. For veterans, this number is especially important because it interacts directly with key veteran benefits like VA home loans and special financing programs designed to honor your service.
Even if you rarely borrow money, your score can still affect your life. A stronger score can mean:
Lower interest rates on car loans and mortgages, including VA-backed loans
Better approval odds for rental housing or utilities with low deposits
More favorable terms on credit cards, including rewards and lower fees
In practical terms, strong financial literacy around credit can save you thousands of dollars over your lifetime. That is money that can stay in your pocket, support your family, or help you reach goals like homeownership, education, or starting a business after service.
Credit Basics: What a Credit Score Really Measures
At its core, a credit score is a prediction: based on your past behavior, how likely are you to repay borrowed money on time? Most lenders in the United States use a FICO or VantageScore model, which typically ranges from 300 to 850. Higher is better, but you do not need a perfect score to get excellent terms. Understanding these credit basics helps you focus on what truly matters for credit improvement, instead of chasing myths or quick fixes that do not work.
Score Range | General Rating | Typical Lender View |
|---|---|---|
300–579 | Poor | High risk, limited approval options |
580–669 | Fair | Some approvals, higher interest rates |
670–739 | Good | Generally favorable terms |
740–799 | Very Good | Better-than-average rates and approvals |
800–850 | Exceptional | Top-tier borrower, best available terms |
As a veteran, you may already be used to clear standards and performance metrics. Think of your credit score in a similar way: it is not a judgment of your character, but a measurement of specific behaviors over time. The encouraging part is that those behaviors can change, and with them, your score can change too.
The Five Factors That Matter Most in Your Credit Score
While different scoring models weigh things slightly differently, most look at the same core pieces of information. Understanding these five factors is the foundation of solid financial literacy around credit and a roadmap for credit improvement.
1. Payment History: Do You Pay on Time?
Payment history is usually the single largest part of your score. Lenders want to see that you pay at least the minimum amount due on time, every month. Late payments, collections, charge-offs, and bankruptcies are all red flags that can drag your credit score down for years. On the other hand, a long record of on-time payments is one of the strongest signals you can send that you are a reliable borrower.
📌 Key Takeaway: Even one payment more than 30 days late can hurt your score. Setting up automatic payments or calendar reminders can protect your record, especially during transitions like PCS moves or separation from service.
2. Credit Utilization: How Much of Your Credit You Use
Credit utilization is the percentage of your available revolving credit—usually credit cards—that you are currently using. If you have a total limit of $10,000 and balances of $3,000, your utilization is 30%. Many experts recommend keeping this below 30%, and lower is generally better for your credit score, especially on individual cards and overall.
For veterans who may have used credit cards heavily during deployments, moves, or periods of transition, targeting utilization is one of the fastest ways to see measurable credit improvement. You do not have to pay everything off at once, but consistently paying down balances can gradually shift your profile from “stretched” to “under control” in the eyes of lenders.
3. Length of Credit History: How Long You Have Been Borrowing
The average age of your accounts also matters. A longer history gives scoring models more data and can signal stability. If you opened your first card while on active duty and have kept it in good standing, that long-running account can be an asset. Closing older accounts can sometimes shorten your average age, so it is worth thinking carefully before shutting down a long-standing card, even if you do not use it often.
4. Credit Mix: Different Types of Accounts
Lenders like to see that you can handle different kinds of credit responsibly. This might include a combination of credit cards, auto loans, student loans, or a mortgage. You do not need every type of account, and you should never borrow just to “diversify,” but a healthy mix can support your score over time, especially when paired with strong payment history.
5. New Credit and Inquiries: How Often You Apply
Each time you apply for certain types of credit, the lender may perform a “hard inquiry,” which can cause a small, temporary dip in your score. Opening several new accounts in a short period can look risky and may lower your credit score, especially if your history is relatively short. This does not mean you should never apply for new credit—just that it is wise to be strategic and avoid a burst of applications all at once unless you are rate-shopping for a single loan like a mortgage or auto loan.
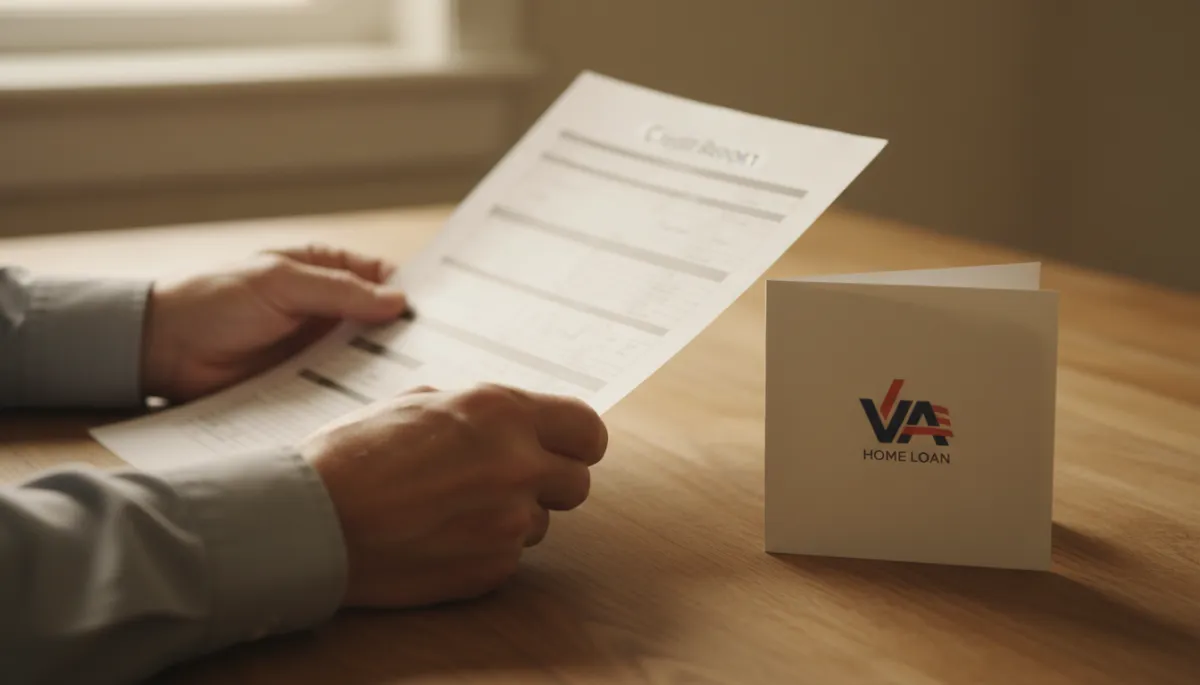
Reviewing your credit report regularly helps catch errors before they affect VA loan opportunities.
How Your Credit Score Connects to Veteran Benefits
Many veteran benefits are not directly tied to your credit score, but several major financial opportunities are. The most important is often the VA home loan program, which offers powerful advantages: no down payment in many cases, competitive interest rates, and no private mortgage insurance requirement. These features can dramatically lower the cost of homeownership compared with conventional loans.
While the Department of Veterans Affairs itself does not set a minimum credit score requirement, private lenders who issue VA-backed loans usually do. A stronger credit score can mean:
Higher odds of being approved for a VA home loan
Lower interest rates, reducing your monthly payment and total interest paid
More flexibility when choosing a lender or loan product
Beyond home loans, your credit profile can influence access to other Veterans Finance programs, such as small-business financing through community lenders, special credit card offers for service members and veterans, and personal loans used to consolidate debt. When your credit is strong, you have more room to choose the options that truly serve your long-term goals, instead of accepting whatever terms you can get.
💡 Pro Tip: If homeownership is a goal, consider checking your credit at least a year before you plan to apply for a VA loan. That gives you time to address errors, pay down balances, and show a consistent pattern of on-time payments.
Building Financial Literacy After Service: Where to Start
Transitioning from military to civilian life often means navigating a new financial landscape: different pay structures, new expenses, and more choices about benefits and retirement. Strengthening your financial literacy—especially around credit—can make that transition smoother and give you more control over your future. The good news is that you do not have to figure it out alone. Many resources are designed specifically for veterans and their families.
Check Your Credit Reports for Free
A smart first step in any credit improvement plan is to see what lenders see. You are entitled to free credit reports from each of the three major bureaus—Equifax, Experian, and TransUnion—through the official AnnualCreditReport.com website. Reviewing these reports can help you:
Spot errors, such as accounts that are not yours or incorrect late payments
Identify high balances that may be hurting your utilization ratio
See how old your accounts are and which ones are in the best standing
If you find incorrect information, you have the right to dispute it with the credit bureau and the company that reported it. Cleaning up inaccurate negative marks can sometimes lead to meaningful credit score gains without changing anything else in your financial life.
Use Veteran-Focused Counseling and Education
Many organizations recognize that veterans face unique financial challenges, from frequent moves to deployments to navigating disability benefits. As part of the broader Veterans Finance ecosystem, you may have access to:
Nonprofit credit counseling agencies that offer free or low-cost budgeting and debt management help
Financial education workshops on base or through veteran service organizations
Online courses and toolkits tailored to veterans and military families
These resources can help translate your existing strengths—discipline, planning, resilience—into a practical plan for managing credit, building savings, and protecting your veteran benefits over the long term.
Practical Credit Improvement Strategies for Veterans
Improving your credit score is not about quick tricks; it is about consistent, manageable steps that align with your real life. Here are practical strategies that many veterans find helpful as part of their Credit Basics toolkit.
Prioritize On-Time Payments Above Everything Else
Because payment history carries so much weight, simply avoiding new late payments can stabilize your score, even if you are still working through old debt. Consider:
Setting up automatic payments for at least the minimum due on each account
Aligning due dates with your benefit or paycheck schedule to avoid cash-flow crunches
Calling creditors if you anticipate difficulty paying; some may offer hardship options that protect your record
Tackle Credit Card Balances Strategically
If high utilization is holding your score back, focus on paying down revolving balances. Two common strategies are:
Debt avalanche: Pay extra toward the card with the highest interest rate while making minimums on others, then move to the next highest rate.
Debt snowball: Pay extra toward the smallest balance to gain momentum and free up cash flow, then tackle the next smallest.
From a credit score perspective, paying a card down below 30% of its limit—and ideally below 10%—can be especially helpful. If you are planning to apply for a VA loan or other major credit within a few months, lowering utilization ahead of time can improve the terms you are offered.
Consider Secured Cards or Credit-Builder Loans if You Are Rebuilding
Some veterans leave service with limited credit history or past challenges like collections or charge-offs. In those situations, traditional cards and loans may be harder to get. Secured credit cards and credit-builder loans can be useful tools for credit improvement:
A secured card requires a cash deposit that usually becomes your credit limit. You use it like a regular card, and responsible use is reported to the credit bureaus.
A credit-builder loan holds borrowed funds in a savings account while you make payments. At the end, you receive the money, and your on-time payments have helped build your history.
⚠️ Warning: Be cautious of high-fee “credit repair” companies that promise overnight results. True Veterans Finance support focuses on education, fair terms, and long-term financial health—not quick, expensive fixes.
Protecting Your Credit and Your Identity as a Veteran
Unfortunately, veterans are often targeted by scams and identity theft schemes. Protecting your identity is part of protecting your credit score and your veteran benefits. If someone opens accounts in your name or misuses your information, the damage can be both financial and emotional—but there are steps you can take to reduce your risk and respond quickly if something goes wrong.
Guard Your Personal Information
Be cautious about sharing your Social Security number, VA file numbers, or account details. Verify that calls, emails, or texts claiming to be from government agencies or lenders are legitimate before responding. When in doubt, hang up and call the official number listed on the agency or company website.
Monitor Your Credit Regularly
Regularly reviewing your credit reports and account statements can help you catch suspicious activity early. Some banks and credit card issuers offer free credit score monitoring tools, giving you another way to keep an eye on changes that might signal a problem.
Know Your Rights If Something Goes Wrong
If you suspect identity theft, you can place a fraud alert or credit freeze with the major bureaus, file a report with the Federal Trade Commission, and contact affected creditors. Acting quickly can limit the damage and help you restore your credit score more efficiently. Many Veterans Finance assistance programs can also guide you through this process, ensuring you do not have to navigate it alone.
Bringing It All Together: A Veteran’s Roadmap to Stronger Credit
Building and maintaining a healthy credit score is not about perfection. It is about understanding the rules of the system, using them to your advantage, and making steady, realistic progress over time. As a veteran, you already know how to follow a plan, adapt when things change, and keep moving forward even when the path is not easy. Those same skills translate directly into effective money management and credit improvement.
The essentials of Credit Basics for veterans come down to a few core practices:
Pay at least the minimum on time, every time, to protect your payment history.
Keep credit card balances as low as you reasonably can, especially before major applications like a VA loan.
Think long-term about your accounts; older, well-managed credit lines are valuable assets.
Be selective about new credit, and avoid unnecessary fees or risky products that promise too much too fast.
Use Veterans Finance resources—counselors, workshops, and nonprofit support—to build your financial literacy and stay informed.
Over time, these habits work together to strengthen your financial foundation. They support your ability to use veteran benefits fully, whether that means buying a home with a VA loan, starting a business, or simply knowing that your finances are stable enough to weather the unexpected. Credit is not the only measure of financial health, but it is a powerful one—and it is within your control to improve it, step by step.
Wherever you are starting from today, your service has already shown what you are capable of. With clear information, steady effort, and the right support, you can bring that same strength to your financial life, build the credit score you deserve, and make the most of every opportunity ahead.
✅ Ready for personalized support? If you want one-on-one guidance to apply these credit basics to your own situation, you can explore financial coaching options at sh-anna-lytics.com/financial-coaching. A dedicated coach can help you build a step-by-step plan that fits your benefits, income, and goals.